Top Reasons Small Businesses Fail in Pakistan and How to Avoid Them
mall business failure in Pakistan often comes from cash flow gaps, weak records and bad partnerships. Real causes, legal lessons and practical fixes
Small Business Failure in Pakistan: 10 Shocking Reasons and Proven Fixes
Introduction
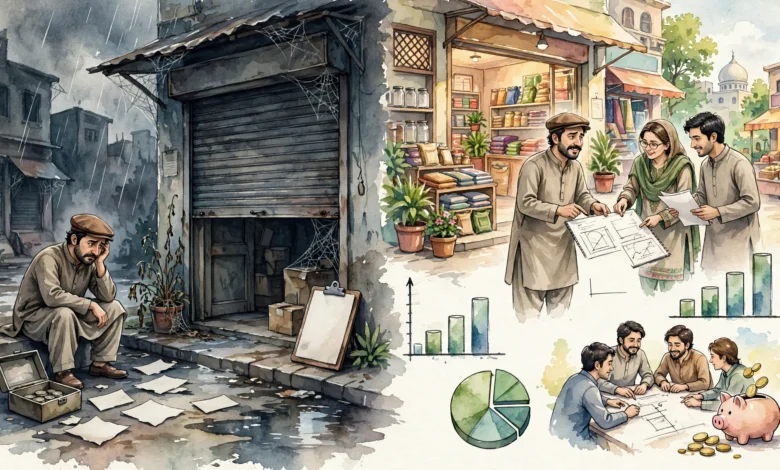
Small business failure in Pakistan rarely happens in one dramatic moment. It usually builds slowly. A bakery in Rawalpindi gives too much credit to regular customers. A garment workshop in Faisalabad takes an order it cannot finance. A tech startup in Lahore burns through savings before finding a single paying client. By the time the owner admits there is a problem, the shutters are already half down.
Pakistan has millions of small and medium enterprises, and they employ a huge share of the workforce outside agriculture. Shops, workshops, food outlets, home businesses and small online stores keep local economies running. Yet many close within their first few years, and the owners often lose family savings, borrowed money and relationships along the way.
Some causes are outside anyone’s control: inflation, power tariffs, political unrest and sudden policy changes. But many are not. Poor cash management, no written records, partnerships built on trust alone, and the temptation to cut legal corners sink more businesses than any economic crisis.
This article looks honestly at why small businesses fail here. It covers the most common reasons, real cases where shortcuts and illegal schemes destroyed businesses and savings, and practical steps owners can take to survive. Whether you run a shop, a factory unit or an online brand, these lessons can help you stay open longer and grow on solid ground.
The Real Business Climate for Small Firms in Pakistan
To understand small business failure in Pakistan, you first need to look at the conditions small owners face every day. These do not excuse bad decisions, but they explain why margins are thin and mistakes get punished fast.
High costs that keep rising
- Electricity and gas tariffs have climbed sharply in recent years. For a small factory, bakery or cold store, the power bill can wipe out a month’s profit.
- Inflation pushes up raw material, rent and wage costs, while customers resist price increases.
- Interest rates have swung up and down, making bank credit expensive in many periods.
A largely informal economy
A large share of the SME sector in Pakistan operates without full registration, proper books or tax filing. This feels cheaper at first, but it locks businesses out of bank loans, large contracts, export orders and government schemes. Informal firms also struggle to sell the business or bring in investors, because there is no reliable record of what the business is worth.
Limited access to formal finance
Most small businesses start with personal savings, family money or informal loans from relatives and committees. Banks often ask for collateral and documented sales. Without these, many owners turn to expensive informal lenders, which adds pressure when sales dip.
Policy and market shocks
Sudden tax changes, import restrictions, currency drops and political unrest can disrupt supply chains overnight. A small importer can see costs jump in a single week when the rupee falls.
The Small and Medium Enterprises Development Authority (SMEDA) offers free pre-feasibility studies, training and guidance that help owners plan around many of these pressures. Very few small owners use it, which is a missed opportunity.
10 Top Reasons for Small Business Failure in Pakistan and How to Avoid Them
Each reason below is common across shops, workshops, service firms and online stores. For each one, there is a practical fix that does not need a big budget.
1. Poor cash flow management
A business can be profitable on paper and still collapse because cash runs out. Owners often confuse sales with cash in hand, mix business and household money, and spend the month’s takings before paying suppliers.
How to avoid it:
- Open a separate business bank account and pay yourself a fixed monthly amount.
- Track cash in and cash out every day, even in a simple register or a free app.
- Keep a reserve of at least two to three months of fixed costs.
- Plan for slow months such as Ramzan for some trades, or post-Eid dips.
Cash flow management is the single skill that keeps most small firms alive.
2. Giving too much credit (udhaar)
In Pakistani markets, credit to regular customers is expected. The trouble starts when udhaar grows faster than sales. Many shopkeepers close with lakhs of rupees owed to them that they will never collect.
How to avoid it:
- Set a credit limit for each customer and stick to it.
- Record every credit sale with date and signature or a message confirmation.
- Stop new credit when old dues pass 30 to 60 days.
- Offer a small discount for cash or digital payment instead.
3. Partnerships without written agreements
Many businesses start between brothers, cousins or friends on trust alone. When profits come in or losses pile up, disagreements about money, roles and ownership tear both the business and the relationship apart. Business partnership disputes are one of the most painful reasons small firms close.
How to avoid it:
- Write a partnership deed and register it with the provincial registrar of firms.
- Clearly define capital, profit share, salaries, roles and exit terms.
- Hold a monthly accounts meeting with all partners present.
4. No proper records or bookkeeping
Without records, owners cannot tell which products make money, where cash leaks, or whether staff are stealing. They also cannot show banks or buyers anything credible.
How to avoid it:
- Use simple accounting software or a free bookkeeping app in Urdu or English.
- Keep all purchase and sales receipts for at least six years.
- Review a basic profit and loss statement every month.
5. Avoiding tax registration
Staying outside the tax net feels like saving money, but it costs more over time. Non-filers pay higher withholding taxes on banking, property and vehicle transactions. They cannot bid for larger contracts, get formal loans or join supply chains of big companies.
How to avoid it: Get an NTN, register for sales tax if your turnover requires it, and file returns on time to appear on the Active Taxpayers List through the Federal Board of Revenue (FBR). Tax compliance is a cost of doing business, and a ticket to bigger opportunities.
6. Starting without market research
Many people open the same business they see doing well nearby: another mobile shop, another burger point, another boutique. The market is already full, and margins shrink for everyone.
How to avoid it:
- Talk to 20 to 30 potential customers before investing.
- Visit competitors and note their prices, quality and gaps.
- Start small, test demand, then expand.
7. Underestimating energy and fixed costs
Owners often plan for rent and stock but forget generators, fuel, UPS batteries, maintenance, security and rising utility bills. These fixed costs quietly eat profits.
How to avoid it: Build a realistic monthly budget, consider solar panels where possible, and choose locations with reliable power for energy-heavy work.
8. Weak customer trust and quality
A customer cheated once tells everyone. Adulterated food, fake branded goods, short weights and broken warranty promises destroy small businesses faster than competition does.
How to avoid it: Keep quality consistent, honour your word, and handle complaints quickly. In local markets, customer trust is your most valuable asset.
9. Ignoring digital marketing and online sales
Customers now search on Google Maps, Facebook, Instagram and Daraz before they visit a shop. Businesses that stay invisible online lose ground to those that show up.
How to avoid it:
- Create a free Google Business Profile with correct address and phone number.
- Keep a basic Facebook or Instagram page updated with real photos and prices.
- Use WhatsApp Business for catalogues and order updates.
10. Expanding too fast
Some owners open a second branch or take a huge order before the first business is stable. Borrowed money, stretched staff and falling quality follow.
How to avoid it: Grow only when the current business runs profitably for at least a year, systems are documented, and you have cash to support the expansion without risking the original business.
When Shortcuts Turn Illegal: Lessons from Real Cases
Some small businesses do not fail because of the market. They fail because the owner, or someone the owner trusted, crossed a legal line. These cases show how fast that can happen.
The Double Shah Ponzi scheme
In Wazirabad, a schoolteacher named Sibtul Hassan Shah, known as Double Shah, promised to double people’s money within weeks. Shopkeepers, farmers and small traders sold land, shops and stock to invest. When police and NAB moved in during 2007, the scheme collapsed. The Express Tribune reported that the scam affected more than 46,000 people, and only a small share had been compensated years later. In 2012 an accountability court sentenced him to 14 years in prison.
The lesson: many small businesses that went under in that region did not fail because of poor management. Their owners pulled working capital out of a real business and put it into a promise of easy returns. If any investment offers fixed, very high returns with no clear business behind it, treat it as a Ponzi scheme.
Religious-branded investment schemes
In the Modarba scandal that came to light around 2012 and 2013, people were offered so-called Islamic investments that promised steady profits. Thousands of savers, including traders, lost money when the schemes collapsed, and NAB filed cases against those involved. The use of religious language made people trust the scheme without checking it.
The lesson: check whether any investment or modaraba is registered with the SECP. A pious name is not a licence.
Online investment and trading apps
In recent years, apps and social media groups have promised daily returns from crypto, forex or “task-based” earning. Regulators have repeatedly warned the public about unlicensed platforms, and the FIA has acted against several. Small business owners looking for quick cash to cover losses are a common target.
Fake invoices and tax fraud
Some traders buy fake sales tax invoices, often called “flying invoices”, to claim refunds or reduce tax. FBR investigations have uncovered networks of fake and inactive companies issuing such invoices. When caught, businesses face back taxes, heavy penalties, frozen accounts and criminal cases. For a small firm, that alone can mean closure.
Adulteration and counterfeit goods
Provincial food authorities regularly seal food units for using unhygienic or adulterated ingredients, and police raid units selling counterfeit branded goods. Each raid destroys the owner’s reputation in the local market, often permanently.
What these cases teach small owners
- Never move working capital into schemes that promise guaranteed high returns.
- Verify any investment or company with the SECP and the State Bank’s lists.
- Never buy or sell fake invoices, even if “everyone does it”.
- Quality and honesty are survival tools, not extras.
Honest businesses still fail sometimes. Dishonest ones fail more often, and they take other people’s savings with them.
A Simple Survival Checklist for Small Business Owners
Use this list every quarter to check the health of your business:
- Business and personal money are kept in separate accounts
- At least two months of fixed costs are saved in reserve
- Outstanding udhaar is under control and recorded
- Partnership terms are written and registered
- Monthly profit and loss is reviewed
- NTN is active and tax returns are filed
- No money is parked in unregistered investment schemes
- Customer complaints are tracked and resolved
- Google Business Profile and social pages are up to date
Frequently Asked Questions
What is the biggest cause of small business failure in Pakistan?
Poor cash flow management is the most common cause. Many businesses make sales but run out of cash because of unrecorded credit, mixed personal spending and no reserve for slow months.
How long do small businesses usually survive in Pakistan?
There is no reliable official figure, because many small businesses are informal and never registered. Owners and trade bodies widely report that the first two to three years are the riskiest.
Is registering my business worth the cost?
For most owners, yes. Registration and tax filing open access to bank loans, larger buyers, government schemes and lower withholding taxes, which usually outweigh the cost of compliance.
How can I check whether an investment scheme is legal?
Check whether the company is registered with the SECP and licensed for that activity. Be very careful with any scheme promising fixed high returns, daily profits or guaranteed doubling of money.
Conclusion
Small business failure in Pakistan is driven partly by tough conditions such as rising energy costs, inflation and limited finance, but most closures trace back to problems owners can control, including poor cash flow, uncontrolled credit, unwritten partnerships, missing records, avoiding tax registration, skipping market research, ignoring fixed costs, weak quality, no online presence and expanding too fast, while cases like Double Shah, the Modarba scandal, fake invoice networks and counterfeit raids show that shortcuts and get-rich-quick schemes destroy businesses even faster, so owners who keep honest books, protect their working capital, stay legally compliant and earn customer trust give themselves the best chance not only to survive but to grow.
Keywords